In Australia, the market has long been dominated by the major banks and mining companies, which now account for about 50% of the ASX 200. In global equities, the Magnificent Seven – all mega-cap technology companies – make up about a third of the S&P 500.
So how do investors gain exposure to powerful structural themes such as AI while still achieving meaningful diversification? And, more broadly, how can they build resilient client portfolios that combine genuinely different sources of return?
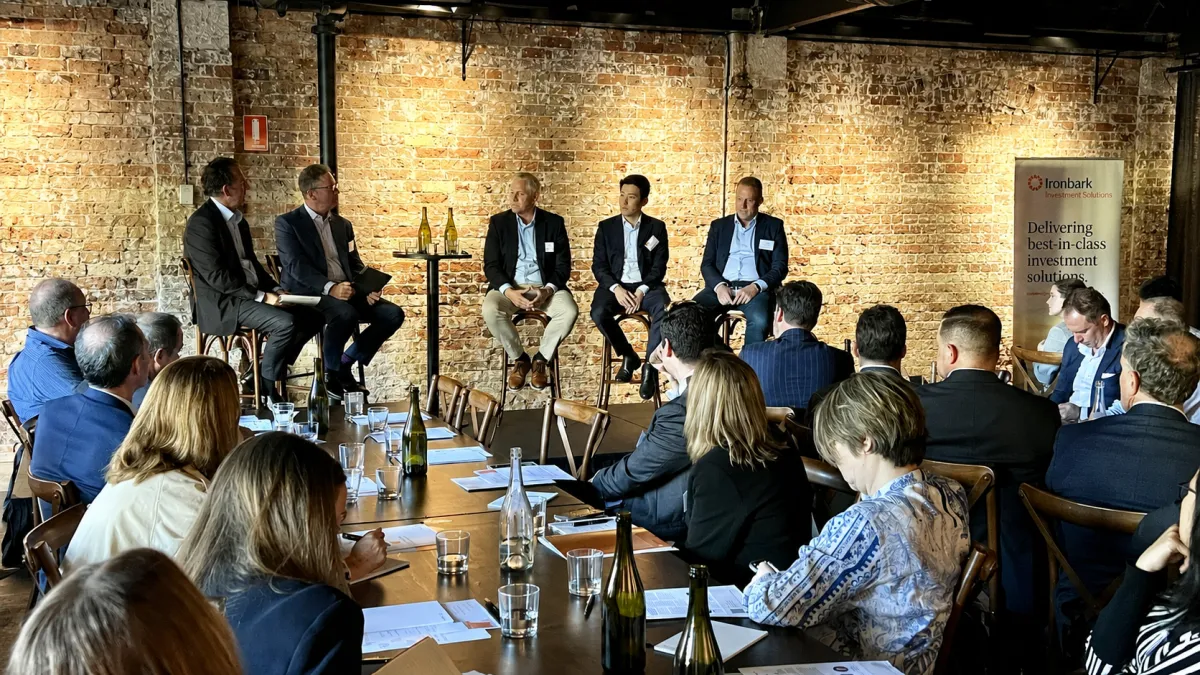
At the inaugural Ironbark Investment Insights Forum, a curated group of global and domestic investment specialists from DWS, Robeco and Infinity came together to explore these questions.
Across two panels, they discussed market concentration, portfolio construction and the opportunities shaping global and Australian markets.
Looking Beyond the Magnificent Seven
For John Vojticek, Head and CIO of Liquid Real Assets, DWS, AI remains a compelling theme, despite much of the attention being focused on a handful of hyperscalers.
He suggests broadening exposure by looking beyond these companies to the ‘picks and shovels’ – real assets, such as copper, power and natural gas.
Data centres also remain compelling, he says. While they already account for around 10% of the global listed real estate benchmark, supply constraints could make existing assets increasingly valuable.
“With the bottlenecks we’re seeing (and even the Governor of Texas in the United States is boasting on X about how he’s stopping data-centre developments) existing assets are going to be worth even more.”
Thinking Smaller for AI
Infinity Asset Management Portfolio Manager Chris Adams comes from a different standpoint.
He acknowledges that large-cap markets are concentrated, but says the problem is far less pronounced in the small and mid-cap space that Infinity favours, both domestically and globally.
“There are no stocks [in our universe] that are bigger than around 1.8% of the index, and you don’t have the same sector distortions you get as you move up the market-cap spectrum,” Adams says.
That doesn’t mean giving up exposure to AI.
Despite US stocks dominating the AI theme, Adams sees plenty of opportunities in Australia, including among the contractors building the data centres.
“Australia imports most of the processing units and technology, but we provide the electrical fit-outs, the buildings and, obviously, the land,” he points out.
There are also the data-centre businesses themselves, such as NEXTDC.
“And one thing Australia does have a strong competitive advantage in is commodities – copper, lithium and other resources needed to support this infrastructure,” Adams adds.
The Emerging Markets Opportunity
For Robeco Client Portfolio Manager Michael Lin, emerging markets provide another way to access the AI theme given that they include some of its most important companies.
“TSMC, for instance, represents around 15% of the emerging markets index and accounts for around 90% of global [advanced semiconductor] manufacturing. It is an essentially irreplaceable part of the AI build.”
But that doesn’t mean investors have to rely on the biggest names. In Robeco’s Emerging Conservative strategy, Lin says, the team aims to maintain diversified exposure across the market, including some 200 stocks, while tilting towards more stable businesses that don’t necessarily make the daily headlines.
One example of a stock the team likes is SK Square. “Everyone knows about SK Hynix – the high-value memory company in South Korea. But you can also get similar exposure through a stock called SK Square that not many people know about,” Lin says.
In fact, SK Square has around 90% of its assets invested in SK Hynix, yet trades at roughly a 50% discount – potentially offering an alternative way to access the same underlying theme at a more attractive valuation, according to Lin.
That said, Robeco also looks further down the AI supply chain – what Lin describes as the “long tail of picks and shovels' stocks”. This includes power and cooling companies, substrate manufacturers and businesses making sub-components used in chip manufacturing.
“As managers, we’re trying to capture opportunities across that entire spectrum,” Lin says.
Broadening the Opportunity Set
But there’s also good reason to look outside AI just now.
DWS’s Vojticek sees opportunities broadening across the property market, particularly in industrial real estate.
Higher interest rates in recent years have slowed construction, with new supply expected to fall to around 1% for industrial and close to zero for retail.
That changing supply picture is particularly significant in the US, which accounts for 70% of the global benchmark. “The big differentiator this year is that the US market is up significantly despite interest rates remaining relatively high,” Vojticek says.
“Regional malls, for example, are among the best-performing property types in the US” - a sector where virtually no new supply is being added.
Commodities and the next cycle
Commodities can’t be ignored either, says Infinity Asset Management CIO Piers Bolger.
“For us, it’s still very much commodities,” he says. “John made the point about dollar debasement and what commodities mean for the future state of the world, which we think is incredible.”
Copper is a case in point. Demand is growing as electric vehicles, AI and data centres require more of the metal. And yet it can take over a decade to get a copper mine up and running.
That combination strengthens the investment case, Bolger argues. “We think the commodity cycle has a long way to go and can sit very comfortably alongside what we’re seeing in AI. From our perspective, it’s just the beginning of that supercycle.”
We think the commodity cycle has a long way to go and can sit very comfortably alongside what we’re seeing in AI. From our perspective, it’s just the beginning of that supercycle.
Building Genuine Resilience
Of course, building resilient portfolios isn’t simply about navigating concentrated markets.
As Ironbark Private Wealth CIO, Chris Ogilvie notes, it is about understanding what you actually own, where the risks overlap and whether your sources of return are genuinely different.
That becomes especially important when markets are stressed.
“You can do all the work on diversification but then have a major market event and suddenly correlations move towards one,” Bolger notes.
That’s why portfolio construction needs to be purposeful, he says. “We look at the whole portfolio outcome rather than focusing on an individual strategy.”
Robeco’s Lin agrees. He points out that two investments can look different on paper but still be exposed to the same economic forces.
“You need to go a level deeper and understand the actual risk drivers of individual stocks – and what happens when you put those stocks together in a total portfolio,” Lin says.
HSBC is an apt example. On the surface it may look like another global financial company, but its underlying exposures can leave it more sensitive to Asian interest rates and economic conditions.
It’s why true diversification should be based on the underlying risk drivers and investment processes, Lin says, not simply labels such as sector, geography, growth or value.
Active vs Passive
It’s not simply a question of choosing active over passive management, however. Rather it’s about where and how to take active risk.
“Every investment decision is an active decision, regardless of how you implement it,” Lin notes.
It’s a point Ogilvie echoes. “It’s not one versus the other; it’s about how you blend them together and get the right attributes.”
That extends to how investors direct their fee budget.
“I think for most people now there’s a realisation that you can take cheap beta in certain asset classes, or across your portfolio, where it makes sense to do so,” Ogilvie says. “At the same time, you want proper alpha that’s worth paying for, rather than quasi-alpha.”
Diversifying the Drivers of Return
For Vojticek, portfolio resilience is also about responding to the current market environment.
Today’s higher real rates, inflation and asset repricing strengthen the case for real assets, as do concerns around the US dollar and rising government spending.
“If you look at the US and what’s happening with the US dollar and fiscalisation, I think assets that can retain their value over time, particularly hard assets, are becoming an increasingly important part of portfolios,” Vojticek says.
Real estate is particularly interesting, he argues, because it has characteristics of both equities and bonds, “with an additional kicker”.
He sees its role within a broader portfolio changing. “Increasingly I think the allocation should come more from fixed income than equities, particularly if we remain in a higher-inflation environment.”
If you look at the US and what’s happening with the US dollar and fiscalisation, I think assets that can retain their value over time, particularly hard assets, are becoming an increasingly important part of portfolios.
A more Purposeful Portfolio
Ultimately, the panel agreed that building resilient portfolios comes down to purposeful investing: being deliberate about where risk is taken, how different investments work together and the role each plays in the overall portfolio.
That inevitably means looking beyond the obvious players.
As Ogilvie says: “I think the moral of the story is: look beyond the big elephants in the room. There are lots of different places where you can gain exposure to these themes, at the right price point with more appropriate diversification.”
Request the Forum Recording
To learn more about the themes discussed and request a recording of the Ironbark Investment Insights Forum (1st September 2026), please contact the Ironbark Investment Solutions team at investmentsolutions@ironbarkfg.com.au.