Getting closer to retirement and looking to boost your super? If you’re 55 or older and thinking about selling your home, you may be able to add $300,000 of the proceeds to your super under the downsizer contribution rules.
For couples, the opportunity can be even greater. Each of you may be able to contribute up to $300,000 from the sale of the same home – adding as much as $600,000 to your combined super savings.
But taking advantage of the rules will be different for everyone. That’s why it’s important to understand how they fit with your broader retirement strategy.
Let’s take a look at how downsizer contributions work and what they could mean for your retirement.
What is a downsizer contribution?
Under the downsizer contribution rules, Australians aged 55 or older can add $300,000 from the sale of their home to their super – so long as they meet the following conditions.
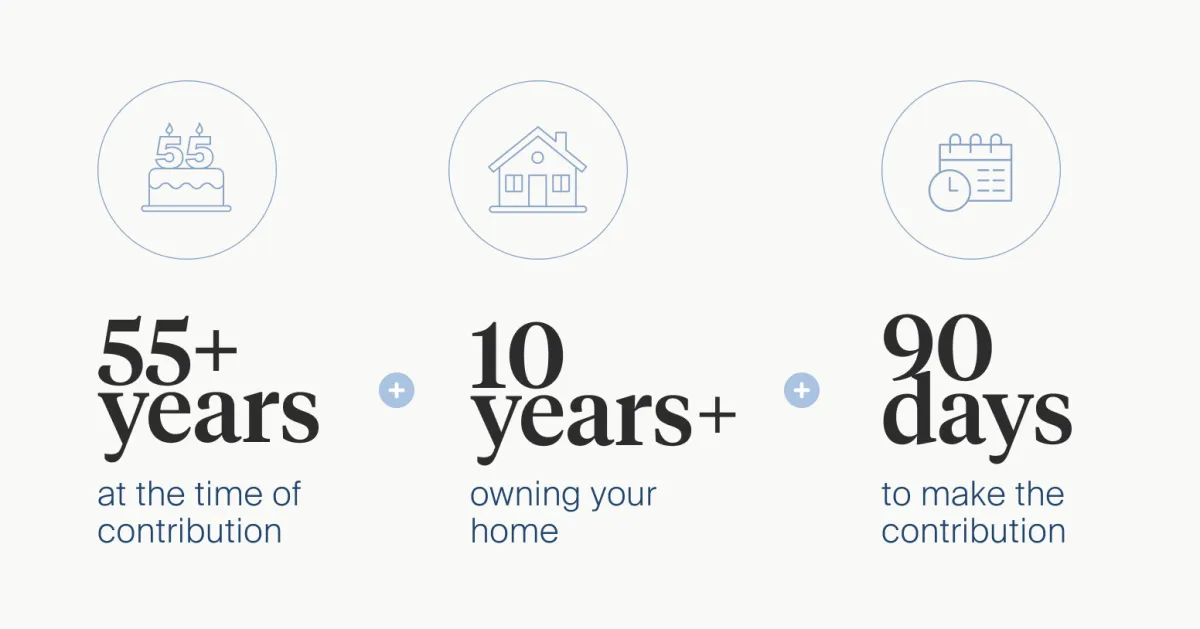
You must be 55 years or older at the time you make the contribution
Your home must have been owned by you or your spouse for at least 10 years, where during some or all this time it was your main residence
It cannot be a mobile home such as a caravan or houseboat, and needs to be in Australia
The contribution must be made within 90 days of the sale, and the super fund must be correctly notified
You cannot have previously made a downsizer contribution from the sale of another home
In addition, the total downsizer contributions made cannot exceed the total proceeds from the home sale. However, you don’t have to buy a new home for the sale to be considered downsizing. Moving into a retirement village or with loved ones, or buying an investment property, are all possible options.
Does it count towards your contribution caps?
One of the biggest advantages of a downsizer contribution is that it doesn’t count towards your annual concessional and non-concessional contribution caps.
That said, you can’t claim a tax deduction for the contribution. Plus, it will be included in your total super balance, which may affect your future eligibility under some super rules and entitlements.
What about the $2 million transfer balance cap?
Like other contributions, the downsizer contribution will count towards your transfer balance cap if you later move it into a retirement phase account.
However, being close to the $2 million cap shouldn’t necessarily put you off making a downsizer contribution. Any amount you can’t move into retirement phase can remain in your accumulation account.
It’s worth keeping in mind when deciding whether a downsizer contribution is right for you.
Could it affect your Age Pension?
Potentially. Your home is generally exempt from the Age Pension assets test, but money held in super can be treated differently.
That’s because once you reach Age Pension age, your super is generally included in the assets test and is also assessed under the income test using deeming rules.
There are also special Centrelink rules to consider. If you sell your principal home, the sale proceeds may be exempt from the assets test for a time. This applies to the portion you plan to use to buy, build, repair or renovate a new principal home.
It’s another reason why a downsizer contribution shouldn't be considered in isolation. The super, tax, housing and social security consequences all need to be considered together.
Is a downsizer contribution right for you?
If you're approaching or already in retirement and thinking about selling your home, a downsizer contribution could provide a valuable opportunity to boost your super.
But the contribution itself is only one part of the decision.
How much you contribute, when you contribute it, what other contributions you make, how much you keep outside super and how the strategy interacts with your retirement income and Age Pension position can all make a difference.
That's why it’s a good idea to seek advice before you sell your home, rather than after you’ve moved your money.
A financial adviser can help you understand how downsizing fits into your broader retirement strategy and make the most of the opportunities available to you.
What does a downsizer contribution look like in practice?
Jessica and Steve are both 60 and have decided their family home is now too big for them. They’ve owned it for more than 20 years and plan to sell and buy a smaller home closer to their kids.
After buying their new home and allowing for other costs, they have $500,000 from the sale to put towards retirement.
Provided they meet the eligibility requirements, Jessica and Steve could each make a $250,000 downsizer contribution. This would allow them to move the entire $500,000 into super without using their normal non-concessional contribution caps.
However, Steve already has $1.9 million in super. That means his $250,000 contribution would take his balance to around $2.15 million, which could affect his ability to make non-concessional contributions in the following financial year.
Jessica, meanwhile, has just $400,000 in super. As a result, she may still be able to make additional non-concessional contributions even after her downsizer contribution. This means it may make more sense for her to add $300,000, from the sale proceeds while Steve contributes just $200,000. Steve can also make a spouse contribution, helping to further boost Jessica’s super.
Before they make their final decision, however, they would also need to consider how much they can move into a retirement income stream as well as any implications for their future Age Pension entitlement.
Super strategies can be complex, and there can be ever more to consider if you have an SMSF. A financial adviser can help you understand your options and build a retirement plan around your circumstances and goals. Contact us at Ironbark Advice today
Interested in making a downsizer contribution?

whether you're eligible to make a downsizer contribution.

how downsizing could affect your super and Aged Pension entitlements.

about how downsizing could fit with your broader financial plan.
Why were the downsizer rules introduced?
Downsizer contributions were originally introduced in 2018 as part of the Australian Government's housing affordability reforms.
The idea was relatively simple: many older Australians wanted to move from a home that no longer suited their needs but faced restrictions on how much of the proceeds they could put into super.
Giving eligible homeowners another way to contribute some of those proceeds to super removed one potential barrier to moving. It also helped free up larger homes for other families.
The rules have since been expanded. When they were introduced, you needed to be at least 65 to qualify. The eligibility age was subsequently reduced to 60 and, from 1 January 2023, to 55.